See your risk before it moves.
A risk management system built for your desk: real-time positions, exposure, margin and payoff, limits that alert before they breach, and a text box where you can just ask. Built over the settlement data you already trust.
Every position, limit and rupee of margin, live.
One screen for the risk team, fed tick by tick from every broker and segment.
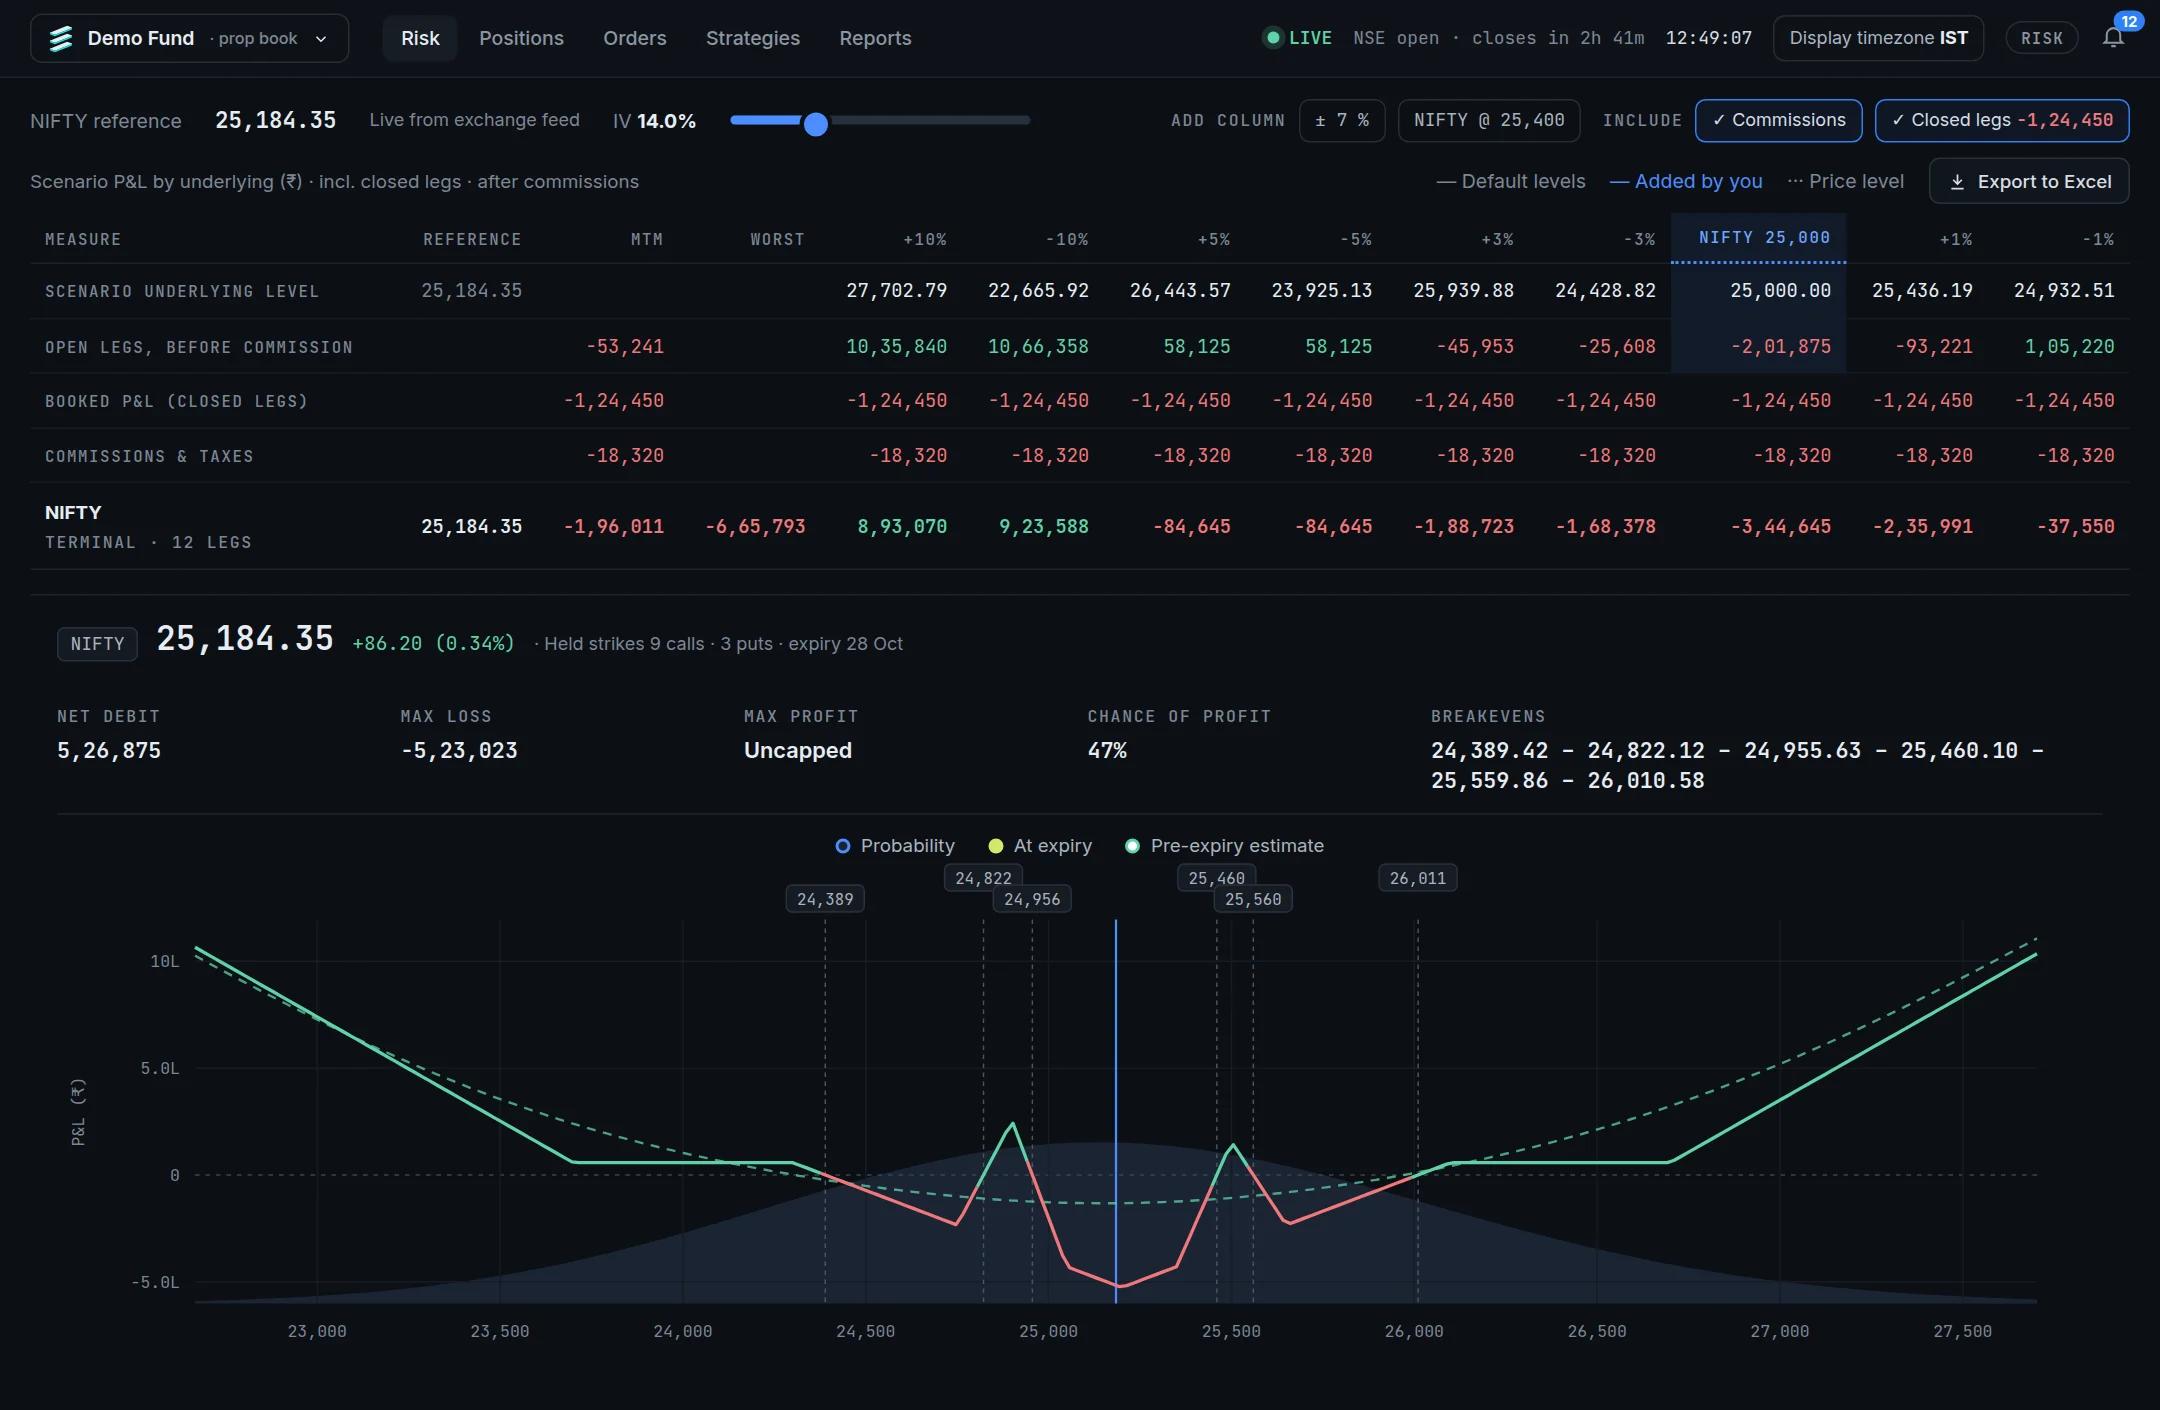
Shown with demo data. Scenario P&L across price moves and a payoff curve with breakevens, for every leg in the book.
Every number a risk desk watches, in one view.
No more stitching exposure together from terminals and spreadsheets after the fact.
Real-time positions
Every leg across brokers and exchanges, netted by strategy, client and underlying.
Exposure and margin
Gross and net exposure, margin used and available, updated as trades fill.
Payoff curves
Strategy payoff at expiry and today, with what-if shocks on price and volatility.
Position sizing
Size suggestions from capital, margin and per-strategy risk budgets.
Limits and alerts
Per desk, trader and strategy limits, alerting on WhatsApp before a breach, not after.
Ask about risk
A text-first interface: type a question in plain language and get the number with its source.
Built on back office
Reads the settlement data that already computes margin interest, charges and profit sharing.
Audit trail
Every limit change, override and alert logged with who and when.
Built for SEBI's algo framework.
SEBI's retail algo framework took effect on 1 October 2025. Brokers act as principals for every algo they offer, and each strategy carries an exchange-issued algo ID. Your RMS should know all of that.
- Algo ID on every orderOrders tagged and checked against the approved strategy list.
- Broker as principalPre-trade checks and kill switches the broker controls.
- SEBI-ready hostingOn MeitY-empanelled Indian cloud, in your name.
On top of your books, not beside them.
Most risk tools want you to export your data into them. We build the RMS over your settlement and back-office records, so the risk view and the books never disagree.
- One source of truthPositions, margin interest, statutory charges and profit sharing from the same data.
- Live alongside existing workflowsNo cut-over: the desk keeps working while the RMS goes live.
- Code you ownFull handover with documentation, plus a fixed AMC.
Live at an arbitrage desk.
from kickoff to a live risk dashboard for Sykes & Ray Equities' arbitrage desk, built on the settlement ERP we had already delivered. Real-time positions, exposure, margin, payoff curves and position sizing. Code owned by SRE.
 Sykes & Ray Equities · arbitrage desk

Need execution too? See sub-10 ms order placement at Statehill Capital.
What desks ask us.
Pair the RMS with our OMS, routing and back office if you need the full stack.
Do we have to replace our back office?
No. The RMS reads from the settlement and back-office data you already trust, through a connector or a direct feed. At Sykes & Ray it sits on top of the settlement ERP we had already built for them.
How fast is it live?
For Sykes & Ray Equities, kickoff to RMS live took 8 weeks. Most of that is agreeing the limit rules and checking numbers against your existing reports.
Where is it hosted?
On a server in your name, on MeitY-empanelled Indian cloud, with access logs and an audit trail. That suits SEBI-regulated entities and keeps position data in India.
Who owns the code?
You do. Code, schema and documentation are handed over, and a fixed AMC covers monitoring, updates and new limit rules.
Show us how your desk tracks risk today.
Send a sample of your positions and settlement reports. We will show you what a live RMS over that data looks like.